
The VIX just posted its third-largest one-day spike since 1990. That wasn’t a fluke, because low volatility always begets high volatility, and history shows what tends to come next.
🏛️ Market Brief – Nvidia Breaks, The Market Holds
In the week the world’s most important chipmaker lost its founder, the S&P 500 still gained 2.5%. The index closed Friday at 7,561.67, erasing most of last week’s VIX-spike damage. The Nasdaq Composite added 2.3% and the Dow 2.1%. Nvidia went the other way. The stock fell 12.8% for the week to $162.85 and now sits 32% below its October 6 record of $239.24.
The shock arrived Thursday. Jensen Huang resigned as CEO, president, and board member, effective immediately, following an independent board investigation into his personal conduct. CFO Colette Kress is now interim CEO. Harvey Jones, the board’s first-ever chair, is running the search for a successor. As we laid out in Nvidia Stock Slides As Huang Exits, the company had no succession plan and no COO. Shares opened down 13%, touched $148.80, and closed down 4.3%. The market isn’t repricing Nvidia’s chips. It’s repricing the uncertainty over who runs the company.

The funding cracks under “the AI trade” widened, too. Thursday’s SoftBank: Another Warning On AI Funding covered SoftBank’s ¥1.1 trillion quarterly loss, roughly $7 billion. Its five-year credit default swaps sit near 500 basis points, the widest since October 2022. OpenAI also pushed its equity offering into 2027, delaying a liquidity event SoftBank was counting on. Yet CoreWeave jumped more than 20% that day on a $132.5 billion backlog. It also carries nearly $47 billion of debt. Such is the market now. It’s sorting AI winners from AI borrowers one balance sheet at a time.
While Nvidia dominated the headlines, the macro data didn’t give the Fed much room. The October CPI report showed a 0.4% MoM increase on Tuesday. Notably, core prices also rose more than expected, up 0.3%. Fed Governor Waller also said that a half-point hike “should be considered” in December.
Furthermore, Friday’s PPI, which rose 0.3%, left producer prices up 6.5% from a year ago. That is the fastest pace since November 2022. Interest rates were noticed: the 10-year yield climbed 29 basis points to 5.15%, the dollar index gained 1.1%, and existing home sales fell to a 3.75 million annual rate, the lowest since August 2010, which tells you exactly where higher mortgage rates are already doing their work.
Even though the market advanced for the week, Nvidia bears watching as it carries one of the largest weights in the S&P 500. It also sits at the center of the capex story behind this year’s earnings growth. Underneath the 2.5% gain, the tape was rotating rather than relaxing. All 11 sectors rose, led by energy at 5.4%. The semiconductor ETF (SMH) still gained 4.9%, even as Nvidia slid. Meanwhile, Bitcoin fell 9.8% to below $70,000, gold lost 4.9%, and the VIX eased to 19.35 from 25.64.
The thread to follow into next week is simple. Nvidia’s Tuesday earnings now carry a leadership question on top of the numbers. Meanwhile, the Fed’s December hike is getting harder to talk the market out of.
📈Technical Backdrop – Above The 200, Stuck Below The 50
The S&P 500 finished the week at 7,561.67, up 2.5% and 3.3% below the October 6 record close of 7,818.93. Monday’s 2.35% gain did most of the work, reversing the prior week’s breakdown in a single session. After that, the rally ran out of buyers. Thursday’s high of 7,653 stopped just short of the 50-day moving average at 7,667. The index then slipped in each of the last two sessions.
While the price action was more bullish, the moving averages tell a split story. The market index currently sits 3.0% above a rising 200-day average at 7,340. This leaves the primary uptrend intact. However, it remains below both the 20-day mean of 7,613 and the 50-day mean of 7,667. More notably, the 50-day has also started to roll over, down from 7,679 a week ago.
Beyond the moving averages, RSI rebounded from 33.5 at the November 5 low to 47, a neutral level with no directional momentum. Furthermore, the MACD remains below its signal line, at −42 versus −41 index points. Nonetheless, the gap has narrowed sharply from a week ago. If the MACD can manage a crossover early next week, it would flip the market momentum signal back to a buy.
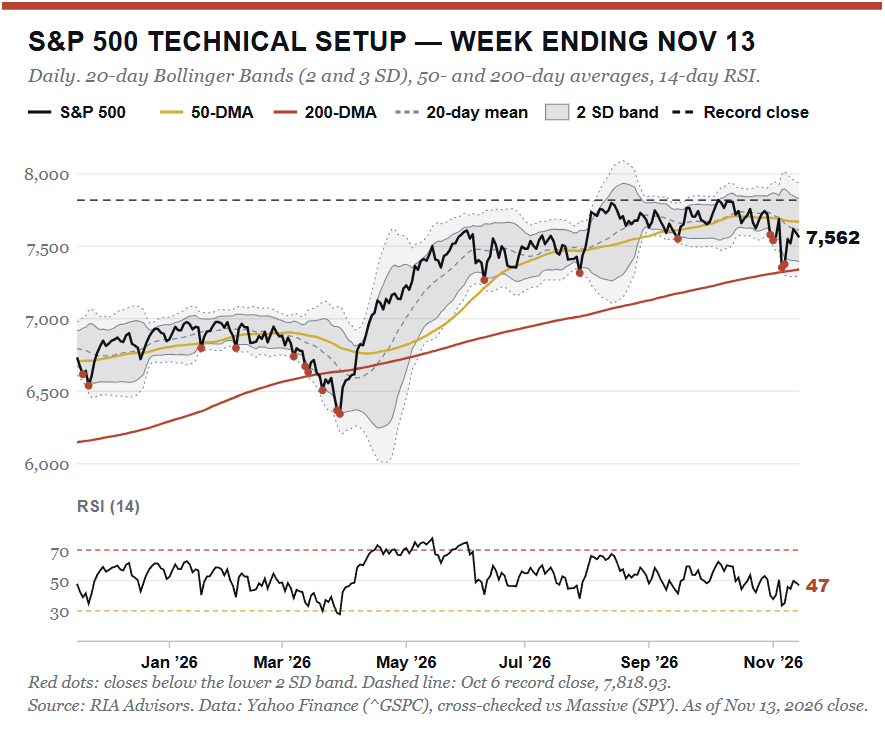
Notice the cluster of red dots at the right edge of the chart above. Four of the six sessions from October 30 to November 6 closed below the lower 2-SD band. That’s the densest cluster since March. The index has since climbed back to roughly half a standard deviation below its 20-day mean. The lower band now sits at 7,396. That’s the level where a retest would look washed out again.
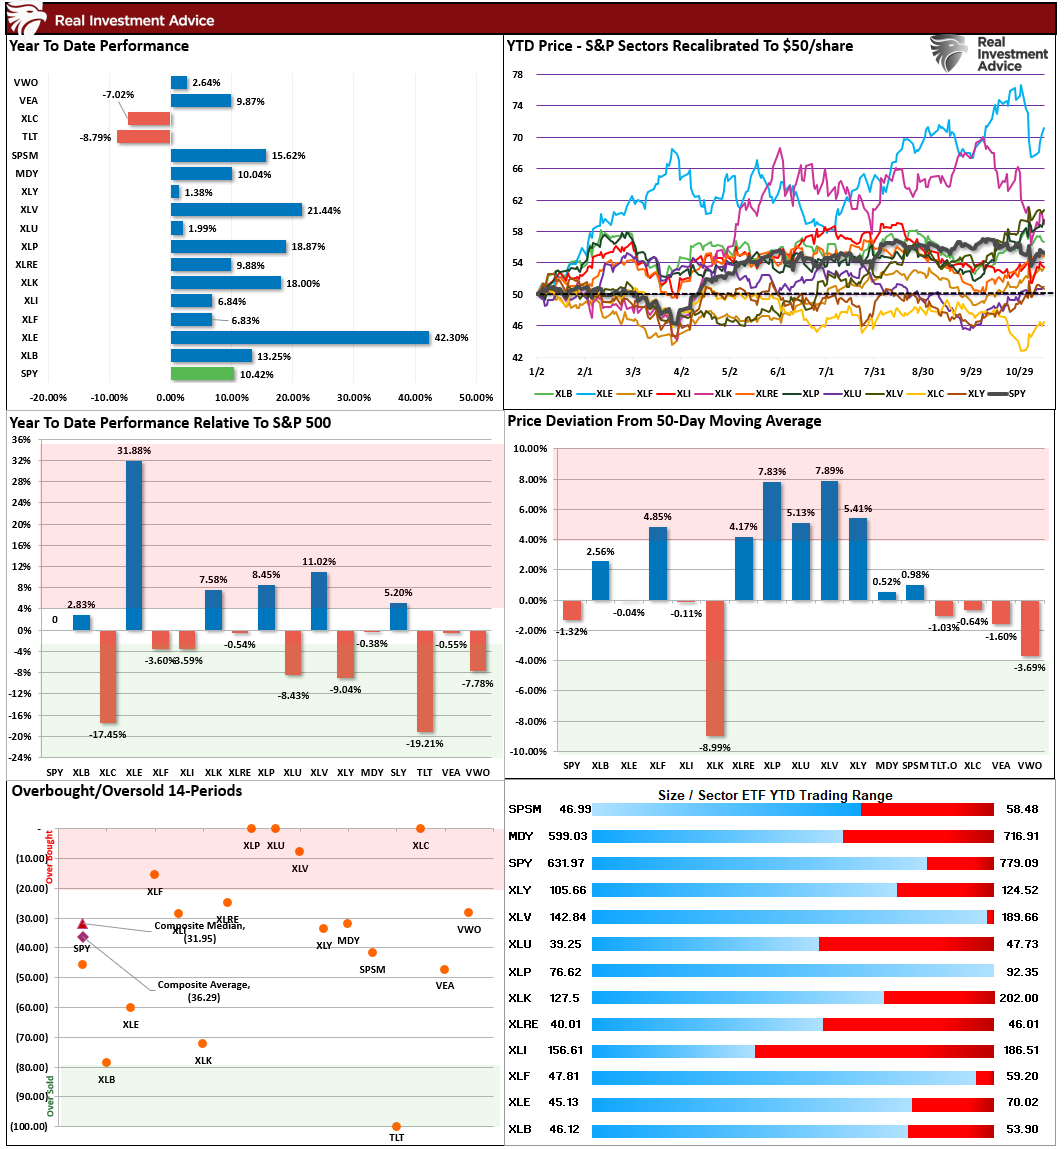
Sector breadth is the strongest evidence this week, and it cuts both ways. Measured against each sector’s 50-day relative trend versus the S&P 500, 10 of 11 sectors are outperforming. Six are more than 5% above trend. Health Care (+9.3%) and Staples (+9.2%) are the most stretched. The equal-weight S&P 500 (RSP) is also 4.2% above its relative trend. That is real “broadening.” The catch is that the only oversold groups, Technology at −7.8% and semiconductors at −11.8%, represent the biggest single block of market value in the index, so the rest of the market can outperform for weeks without lifting the S&P 500 to a new high.

The bullish case making the rounds this week is simple. If 10 of 11 sectors are beating the index, the market must be healthy. It is, below the surface. But a cap-weighted index can’t make a new high while its largest sector sits 8% below trend. Either technology catches up to the market, or the market comes down to meet technology. Such is why Tuesday’s Nvidia report matters for the whole tape, not just for one stock.
For shorter-term traders, the investing playbook for next week is fairly straightforward. If the market can close above the 50-day at 7,667, it would reopen the path to the record at 7,819. For now, Initial support is Friday’s low near 7,500, but below that, the 200-day average and the November 5 low converge at 7,340 to 7,350.
Most crucially, a close below July’s swing low at 7,316 would break the pattern of higher lows. Such a break would argue for raising cash and adding hedges to portfolios. For now, until the index reclaims the 50-day, we continue to recommend trimming extended defensive positions as strength develops. We are looking to add to growth stocks but only in measured tranches with confirmation, not on a bounce that has already stalled once.

In summation, the single level to watch this coming week is the 50-day moving average at 7,667. The index failed there on Thursday, raising our caution level. A second failure after Nvidia reports would turn a healthy pullback into a range-bound year-end.
🔑 Key Catalysts Next Week
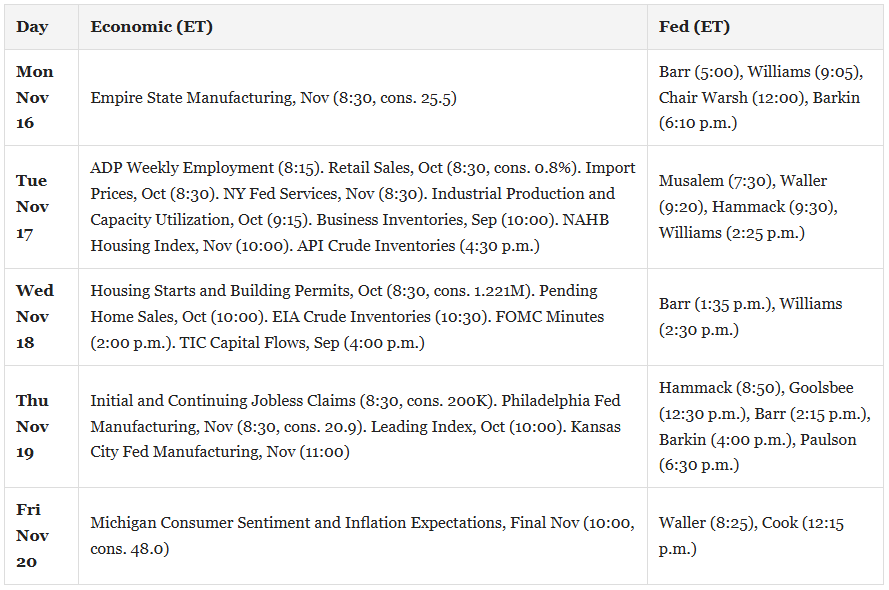
This coming week, two stories will move the markets. The first, as noted, is Nvidia’s first earnings report without Jensen Huang. The second is a Fed that keeps telling markets a December hike is coming. Nearly everything else on the calendar feeds one of those two narratives.
Nvidia reports fiscal third-quarter results Tuesday after the close. Consensus expects about $2.49 per share on revenue near $109 billion. That sits slightly above the company’s own guidance of roughly $108 billion. The numbers matter less than usual this time. Investors will want three things: guidance, how much of the backlog leans on customer financing, and what Colette Kress says about the CEO search. Whether the House appearance requested of Huang for November 18 will still take place is now unclear.

Moreover, the Fed calendar is very crowded. Chair Kevin Warsh speaks Monday at noon ET. Then John Williams speaks Monday, Tuesday and Wednesday. Christopher Waller, who floated a half-point hike after CPI, speaks Tuesday and Friday. The October FOMC minutes land Wednesday afternoon. Futures still price a hike at the December 8 to 9 meeting, so any speaker leaning against it would be news. Such is the bar for a dovish surprise right now: one Fed official merely sounding patient would count.
Notably, the data slate this coming week will center on the consumer. October retail sales arrive Tuesday with consensus at 0.8%, alongside industrial production. Home Depot and Disney report Tuesday morning, then Lowe’s, Target and TJX on Wednesday. Walmart closes the retail circuit Thursday morning. Housing starts follow on Wednesday, after this week’s dismal existing-home sales report. Thursday brings jobless claims and the Philadelphia Fed survey, and Friday wraps up with the final Michigan sentiment read.
Most importantly, pay close attention to the retail sales control group. The core retail sales group excludes autos, gasoline, and building materials. This particular reading is what feeds directly into GDP. With mortgage rates above 7% and consumer prices still rising 0.4% per month, a soft number would be the first clear sign that higher rates are finally reaching shoppers.
The Nvidia earnings report on Tuesday, followed by a Congressional hearing on Wednesday, is the event that moves everything else, and the asymmetry runs both ways. Weak guidance on top of a leadership vacuum would confirm the market’s repricing. A poor hearing on top of that will likely pull the index back toward its 200-day average. Unfortunately, the upside case is less obvious. However, a clean beat, credible financing commitments, and a calm succession process, with the stock already deeply oversold, could find buyers, at least temporarily.
Need Help With Your Investing Strategy?
Are you looking for comprehensive financial, insurance, and estate planning services? Need a risk-managed portfolio management strategy to grow and protect your savings? Whatever your needs are, we are here to help.

💰 VIX Spike Was Complacency’s Bill Coming Due
On Wednesday, November 4, the S&P 500 delivered what Fortune called the best post-midterm rally in 44 years, and the VIX closed at 16.61. It was only a moment of bliss as the market plunged nearly 5% the following day. On Thursday, the VIX spiked, closing at 28.18. That 69.7% VIX spike was the third-largest one-day jump since 1990, trailing only February 2018 and December 2024. As we covered in last week’s Midterm Election Goes Blue, the election supplied the headline, and leverage supplied the selling. None of that should surprise anyone. What should get your attention is how reliably this sequence repeats.
Complacency Always Ends, And It Usually Ends Fast
Look at what came before Thursday. Over the prior 63 trading days, the VIX averaged 16.2 and closed below 17 on 48 of them. It bottomed at 14.21 on September 22, with the S&P 500 near 7,765. Meanwhile, hedge fund gross leverage was near 310%, a five-year high, according to Goldman’s prime book. Such is what “calm” looks like right before it isn’t.
The economist Hyman Minsky spent a bulk of his career on one idea: stability breeds instability. The reason is that when volatility stays low, “risk models” tell investors that they can safely carry more equity exposure. For example, volatility-targeting funds will mechanically add leverage, while option sellers collect premium that feels like “free money” because nothing ever seems to happen. Every one of those decisions makes sense. However, when combined, they create a market in which one bad headline sends everyone toward the same narrow exit at once.

Look at the chart above, and notice that the shaded stretches mark every period since 1990 when the VIX averaged below 15 for roughly three months. Each one ended the same way, with a burst of outsized daily swings in both directions: 1997 and 1998 after the mid-1990s calm, 2008 after the 2004 to 2007 lull, 2018 after the quietest market in a generation, and 2025 after the calm of early 2024. The best days and the worst days arrive together, and they arrive after the calm.
Low volatility hides risk while investors quietly pile more of it on.

Notice the starting points in the chart above. Seven of the ten largest one-day VIX spikes since 1990 began with the VIX below 20, including this one. The February 2007 spike started from 11.15. The biggest surges don’t come from markets that are already scared. They come from markets that stopped worrying.
Why Ultra-Low VIX Readings Are A Warning, Not A Confirmation
A reader wrote in a few months ago with a fair question: “If the VIX is low, investors are confident, so isn’t that bullish?” It sounds right. The problem is what the VIX actually measures. It’s the price of portfolio insurance. A low reading tells you insurance is cheap; therefore, a low VIX tells you protection is on sale. It says nothing about whether you’ll need it.
The following data makes the point clearly. Going back to 1990, I ran every trading day and asked how often the VIX at least doubled within the following twelve months, sorted by where it started. There are two important findings worth noting.
- From readings under 12, it doubled 72% of the time, and the median peak ran 2.2 times the starting level.
- When readings were above 35, it doubled just 3% of the time.
In other words, volatility can’t fall much below 10. However, it can easily triple from those levels. That asymmetry is the whole story.

This is where Bob Farrell’s Rule #1 reminds us that markets return to the mean over time. Importantly, the “mean reversion” idea applies to volatility as well, without exception. Low volatility begets high volatility because the calm itself encourages the behavior that ends it. That’s why the time to BUY protection is when the VIX is sleepy, and nobody wants it.
What Stocks Did After The Biggest VIX Spikes
Here’s the good news. Historically, fear spikes like this one have been better entry points than exit points. After the ten prior one-day VIX spikes of 50% or more, the S&P 500 averaged 2.8% one month later and 12.0% a year later, higher in eight of ten cases. Widen the net to all 24 prior spikes of 40% or more, and the twelve-month gain averaged 18.8%, with 22 of 24 higher. For comparison, a random day since 1990 produced 10.2% over the next year, positive 81% of the time.
This is why you have to be very careful with “averages,” as they hide the path. The November 2021 spike was followed by a 13.7% loss over the next year, because it ran straight into the Fed’s 2022 hiking cycle. With December hike odds near 99% after Tuesday’s CPI report, that’s the analog I’d watch most closely. The path also gets choppy even when the destination is fine. After December 2024, investors still had to sit through the April 2025 selloff.
That brings us back to a point we made in 10 Best Days: A Meme For Every Bull Market. As shown in the daily price changes chart above, those “best days” cluster right next to the “worst ones.” Monday’s 2.35% gain was the best session since April, and it came two trading days after the worst session since April 2025. Selling in a panic means missing the rebound. The real lesson is to manage risk before the spike, while protection is cheap, rather than after it arrives.
Why The Setup Still Favors Rotating From Value Back To Growth
This week’s Daily Market Commentaries laid out why the conditions for a rotation back toward growth are mostly in place. Technology’s RSI sat at 29 on Friday, and semiconductors closed 31% below their June high, a bear market by any definition. In Tuesday’s commentary, we showed that tech went from 17% above its decade-long relative trend on October 2 to 6% below it five weeks later. The entire 2026 premium is gone. Yet operating income for eight AI leaders rose 71% from a year ago in the second quarter. Prices broke. Earnings didn’t.
Positioning is the other half. Hedge fund nets sit at five-year lows, long/short funds just made the largest gross exposure cut since Covid, and Thursday was the biggest put-buying day in CBOE history. Trend-following CTAs sit at −3.3 standard deviations on U.S. equities, roughly the 1.9th percentile of the past year. Meanwhile, Health Care is more than 15% above its 200-day average, a stretch seen only twice since 2005. The forced sellers have mostly sold, and the “safe” trade is now the crowded one. That’s why our factor rotation model flipped from value to growth last week, following the setup we outlined in Value Had Its Run.

Someone will tell you that oversold can always get more oversold. They’re right. The Nasdaq 100 (QQQ) is still sitting just under its 200-day average, and as we noted in Is Nvidia Still Cheap?, the bounce gets the headlines, but the reclaim is the signal. Nvidia reports on November 17, and Jensen Huang has been asked to appear before three House committees the next day. Such is the risk with washouts, which tend to feel finished right before the retest. Credit spreads have also widened by about 60 basis points over six weeks, which so far looks like repricing rather than a break.
What Should Investors Do After A VIX Spike?
History tilts the odds toward higher prices from here, and November through April has been the strongest stretch of the year in midterm cycles. Odds aren’t a plan, though. Here is how we are approaching the rest of the year.
The best time to prepare for volatility is when nobody thinks they need to.
Thursday following the election was a strong reminder that markets don’t send invitations before they reprice risk. Unfortunately, the investors who got hurt the most weren’t wrong about AI. They simply carried too much leverage into a quiet tape and assumed the quiet would last. Rebalance into strength, keep your stops honest, and when the VIX spike settles back into the low teens, resist the urge to believe it will stay there.
The VIX will be back in the low teens soon enough. That’s when the next bill starts coming due.
🖊️ From Lance’s Desk
This week’s #MacroView blog explores the world of bonds. What are they, how they work, what determines yield, and how they work in a portfolio.

Also Posted This Week:
- Buying Bond Exposure Without Buying Bonds– by Michael Lebowitz
- Recession Indicators Turned Green. Job Quality Hasn’t. – RIA– by Lance Roberts
📹 Watch & Listen
Stock market volatility is rising as NVIDIA’s sharp decline threatens the market’s recent recovery. After successfully testing its 200-day moving average, the S&P 500 has recovered nearly all its post-election losses but now faces renewed resistance at its 20-day and 50-day moving averages.
Subscribe To Our YouTube Channel To Get Notified Of All Our Videos
📊 The Weekly Market Dashboard
Weekly technical overview across key sectors, risk indicators, and market internals

💸 Market & Sector X-Ray: Market Gains Ground
Despite all the turmoil following the elections, the market rallied enough last week, to keep the market within the ongoing consolidation of the past six months. The successful test of the 200-dma is encouraging, but we need to see some follow through buying and a pick up in the Technology sector if we are going to move the markets higher into year-end.
📐 Technical Composite: 47.39 – Buyers Return As Expected
The technical condition improved a bit last week after the post-election plunge. As noted last week, “However, the reduction reversed the previous overbought condition back to more extremely oversold typically precedes rallies.” We saw a bit of a rally last week, and could get some follow through this coming week. Rebalance risk and remain tactically cautious until conditions improve further.

🤑 Fear/Greed Index: 55.08 – Holding At Neutral
With the broader market rallying last week, outside of Technology, the underlying market allocation and sentiment remain more neutral although rising a bit from last week. There was an increase in the Commitment of Traders equity allocations; however, investor sentiment remains more bearish. With the market still decently oversold short-term, a further bounce is possible.

🔁 Relative Sector Performance
As shown below, the Healthcare, Staples, Financial and Real Esate have become more overbought, while the Technology is the most oversold. Historically, these more extreme deviations, as noted last week, have been a precursor to a rotation, while that didn’t happen this past week, doesn’t mean it won’t.

📊 MFBR Index (Money Flow/Breadth Ratio Indicator)
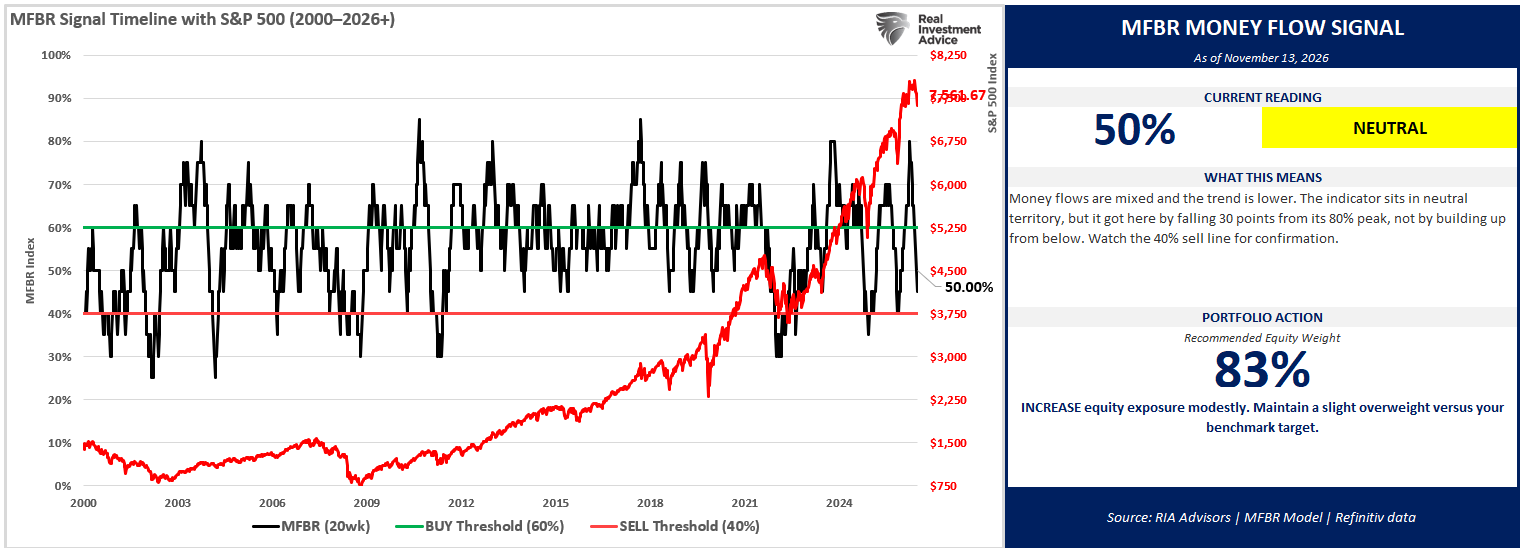
The Money Flow Breadth Ratio (MFBR) model is a rules-based equity allocation framework that uses weekly S&P 500 money flow data to generate buy, sell, and neutral signals. The MFBR systematically adjusts portfolio equity exposure in response to the direction and persistence of institutional capital flows. It aims to reduce drawdowns while capturing the majority of market upside.
“As of November 13, 2026, with the S&P 500 at 7,561.67, the Money Flow Breadth Ratio (MFBR) stands at 50%, down from a peak of 80% set 13 weeks ago and rising versus 45% the prior week. The trailing four-week change is -5 percentage points, and the near-term trend has rolled over. This places the indicator in the 50-60% range. The raw zone signal reads NEUTRAL, but the model still flags a TOP REVERSAL, with 30 points now off the peak. Read that NEUTRAL as a zone label, not as fresh confirmation – the model reached this band by falling out of overbought, not by building up from below.
Bottom line: hold the target weight. The roll-over off the 80% peak is real and worth watching, and it has now carried the gauge into the 50-60% band. Falling readings here have still averaged +5.2% over 26 weeks with a 73.1% win rate, so this is neither a chase nor a de-risk. A break below 50% would cut the grid to 58%; a move back above 60% would restore a full overweight.”
📊 Sector Model & Risk Ranges
We noted last week that “Energy remains extremely elevated above long-term means, and Healthcare has now joined that club.” It is worth rebalancing risk after last week’s rally, outside of Technology. Communications, Industrials, Discretionary, and Financials are extended. Continue to rebalance risk, as we still expect the rotation to Technology, in particular, to occur.

Have a great week.
Lance Roberts, CIO, RIA Advisors